How does excess inventory affect fashion retail profitability?
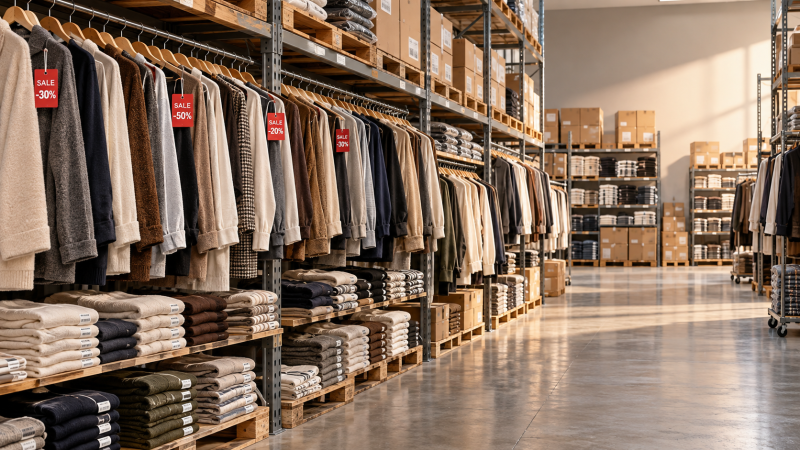
Excess inventory can quietly erode fashion retail profitability long before unsold products leave the warehouse. Markdowns reduce margins, while storage costs, tied-up working capital, and shifting trends add financial pressure. For business leaders, the challenge is not simply to sell more stock. It is to align buying, production, and demand planning with changing customer behavior—and to recognize when a product needs intervention before its value falls further.
The financial impact is rarely visible in a single line of the income statement. An overbought collection may appear manageable while sales continue, yet it can absorb space, delay new arrivals, and leave less cash available for the products customers actually want. Understanding those connected effects makes inventory decisions more useful than reacting to the latest stock total alone.
Where excess inventory takes its toll
Excess inventory is stock that exceeds expected demand within a commercially useful selling period. That does not mean every unsold item is a problem. A black T-shirt with consistent demand may be worth holding, while a highly seasonal print can lose relevance quickly. The important question is whether the expected return from keeping an item justifies the cash and capacity it consumes.
Markdowns reduce the profit earned on each sale
Discounting is often the most visible cost. A lower selling price narrows the gap between revenue and the cost of the product, and additional promotion or fulfillment expenses can reduce the contribution further. Deep discounts may also shift customers away from full-price purchases if shoppers come to expect regular clearance events.
Consider an illustrative item that costs $40 and sells for $100. Before other expenses, its gross profit is $60. If it sells at a 40% discount, revenue falls to $60 and gross profit drops to $20. The retailer still makes a sale, but it needs to sell three discounted units to generate the same total gross profit as one full-price unit. This simplified comparison excludes returns, shipping, and other costs.
Cash becomes harder to deploy
Inventory ties up money that could otherwise support replenishment, marketing, debt reduction, or investment in a stronger product line. This matters even when stock is not yet discounted: the cash has already been committed, while the timing and value of future sales remain uncertain.
For a growing retailer, the trade-off can be particularly uncomfortable. Popular sizes may sell out while capital remains locked in slow-moving colors or styles. Ordering more of the winners then requires additional financing or cuts elsewhere, despite a warehouse that looks full.
Holding stock creates ongoing costs
Warehousing, handling, insurance, inventory management, and transfers between locations all add to the cost of keeping goods. Fashion products can also deteriorate, become damaged, or require repackaging. When warehouse capacity is constrained, slow stock may force a retailer to pay for overflow space or handle goods more often than planned.
Accounting treatment varies, so leaders should distinguish between costs included in inventory valuation and operating expenses recorded separately. Either way, those costs affect the economics of the decision to hold or clear the stock.
Product value can decline before anyone changes the price
Fashion demand is time-sensitive. Weather, social trends, competitor activity, and the arrival of a new season can all shorten an item’s selling window. Inventory may therefore need a write-down if its recoverable value falls below its recorded value, subject to the applicable accounting framework. The eventual loss is not always limited to the markdown: disposal, donation handling, or other exit costs may also matter.
Measure the problem at product level, not just company level
An overall inventory balance can hide very different risks. A business may have too much stock in one region and too little in another, or have a healthy total number of units but a poor size mix. Decision-makers need a view by style, color, size, channel, location, and age, with enough context to distinguish a temporary slowdown from a genuine demand shift.
Several measures are especially useful when reviewed together:
- Sell-through rate: Units sold divided by units available for sale over a defined period. Compare it with the planned pace for that product and season, rather than treating one threshold as universal.
- Inventory turnover: Cost of goods sold divided by average inventory at cost for the same period. A slowing rate can signal excess stock, but interpretation should account for seasonality and planned inventory builds.
- Weeks of supply: Current available units divided by expected weekly unit sales. Use a realistic forward sales estimate; if demand is highly uncertain, test more than one scenario.
- Inventory aging: Stock grouped by time since receipt or another consistent starting point. Aging shows where intervention may be needed, but an older core item is not automatically obsolete.
- Gross margin return on inventory investment: Gross profit divided by average inventory at cost. This connects the margin earned with the capital employed, provided both figures cover the same period.
No metric should become a target in isolation. Faster turnover achieved through heavy discounting may damage profit, while a high gross margin percentage on a small volume can conceal poor cash productivity. Include returns, canceled orders, and transfers in the analysis so reported demand is not confused with demand that the business can profitably fulfill.
Decide whether to hold, move, promote, or exit
Once excess stock is identified, the next decision is economic rather than emotional. A buyer may believe in a collection, and a merchant may be reluctant to discount it, but the relevant comparison is between the expected outcomes from today onward. The original purchase cost is important for reporting; it should not, by itself, dictate whether more money is spent holding or promoting the product.
A targeted approach usually gives leaders more control than a blanket sale. A slow size in one store might sell at full price online, while a trend-led item with weak demand across all channels may need an earlier exit. Compare the expected net proceeds of each option, including the cost of waiting. A smaller discount now can sometimes produce a better result than a deeper discount after the season has passed.
There are risks in moving too quickly, too. Frequent promotions can undermine price confidence, and shifting stock between locations without evidence of demand simply relocates the problem. Set a review date for held or transferred inventory and define what sales pace would trigger the next action.
Prevent overbuying without creating constant stockouts
Reducing excess inventory is not the same as minimizing inventory at all costs. Underbuying can mean lost sales, emergency freight, and disappointed customers. The aim is to place risk where the business can manage it: commit carefully when demand is uncertain, and preserve the ability to respond when demand becomes clearer.
Separate predictable demand from fashion risk
Core replenishment items and trend-led collections need different buying logic. For established basics, historical sales, availability, and replenishment lead times can provide a useful starting point. For new styles, history is less reliable. Smaller initial orders, planned tests, or staged commitments may limit exposure, provided suppliers can support the required timing and quantities.
Forecasts should reflect events that distort the past, such as stockouts, unusual promotions, or late deliveries. If a popular size was unavailable for several weeks, recorded sales alone will understate demand. Equally, a promotional spike should not automatically become the baseline for the next order.
Build supply flexibility into purchasing decisions
Supplier terms affect how much forecast error a retailer must absorb. Review minimum order quantities, production lead times, cancellation windows, material commitments, and the feasibility of repeat orders. A lower unit price may be attractive, but it can prove costly if it requires buying far beyond credible demand.
Collaboration matters here. Merchandising, finance, sourcing, and operations should assess the full commitment, including fabric or component purchases made before finished goods are ordered. Flexible capacity may carry a premium, so compare that premium with the potential cost of excess stock and missed sales rather than assuming either option is always cheaper.
Use early signals, not just end-of-season reports
Monitor sales against the planned curve soon after launch. Look for weak performance by size or channel, unusually high returns, and differences between customer interest and completed purchases. These signals can inform allocation, product presentation, replenishment, and pricing while there is still time to act.
Early intervention does not mean reacting to every quiet day. Agree on review intervals and decision rules that reflect the product’s selling window and normal volatility. Document the reason for each action, then compare the outcome with the original forecast. Over time, that feedback can improve both the forecast and the judgment around it.
Make inventory risk a shared financial decision
In fashion retail, excess stock often begins with a reasonable decision made in one part of the business: a larger order to secure a better cost, a broad size range to protect availability, or an ambitious forecast for a new collection. Problems emerge when the resulting risks are not visible across teams.
A practical leadership review should bring together the value and age of stock, expected demand, margin after likely interventions, available cash, and upcoming supplier commitments. Assign an owner to significant exposures and distinguish decisions that can be reversed from those that cannot. That makes it easier to protect availability where it earns a return and act decisively where it does not.
The goal is not a perfectly empty warehouse. It is an inventory portfolio that supports customers, releases cash at a useful pace, and earns enough margin to justify the space and capital it occupies.
Recommended News
 Why do automatic mechanical watches stop when not worn?Why do automaticmechanicalwatches stop when unworn? Discover how power reserve works, how to restart your watch, and when to seek professional help.
 Choosing high-tensile bolts for industrial fastening in EuropeIndustrial fastening Europe: Learn how to select high-tensile bolts, coatings and standards for reliable joints, accurate preload and safer assembly.
 How does excess inventory affect fashion retail profitability?Discover how excess inventory erodes fashion retail profits through markdowns and holding costs, and learn practical ways to protect margins and free up cash.
 US Adds 50% Section 338 Tariff on Canadian Seals and Other ProductsUS Section 338 tariffs add 50% to covered Canadian seals, lubricants and other goods. Explore the potential impact on sourcing and supply chain costs.
 Can lean manufacturing reduce changeover time in injection molding?Discover how lean manufacturing can reduce injection molding changeover time with SMED, better preparation, standardized processes, and quality controls.
 How to estimate the payback period for a CNC machining centerEstimate your CNC machining center investment payback with a practical formula, installed cost checklist, cash-flow examples, and risk analysis.
 How cloud computing supports remote CNC machine monitoringDiscover how cloud computing enables remote CNC machine monitoring, from real-time alerts and troubleshooting to secure integration and smarter pilot decisions.
 LANXESS and BPCL to Explore Immersion Cooling Fluids and Advanced LubricantsLANXESS and BPCL are exploring immersion cooling fluids and advanced lubricants. Discover what the proposed collaboration could mean for buyers and suppliers.
 What OEM manufacturing support is needed for smart actuator testing?Explore OEM manufacturing support for smart devices: precision fixtures, firmware access, load testing, and traceable results. Learn what to demand for reliable smart actuator validation.
 How minimum order quantities affect wholesale bedding set costsBuying bedding sets wholesale? Discover how minimum order quantities affect unit prices, inventory risks, and total costs—and learn to negotiate smarter deals.
 What should mechanical seal technical specification documents include?Explore technical specification support documentation for mechanical seals, covering materials, drawings, standards, and testing to reduce risks and make confident supplier approval decisions.
 Shanghai Plan Targets Ultra-Precision Machining and Five-Axis Machine Tool UpgradesShanghai's ultra-precision machining and five-axis machine tool upgrade priorities could shape equipment investment. Explore potential opportunities and what buyers should verify.
 How global trade tariffs affect the landed cost of injection moldsDiscover how global trade tariffs affect injection mold landed costs. Compare duties, freight, and customs rules to avoid hidden expenses and make smarter sourcing decisions.
 How to qualify a catalyst manufacturer for synthetic oil productionQualify a catalysts manufacturer for synthetic oil production with practical checks for performance, batch quality, and scale-up. Learn how to reduce risk and select a reliable supplier.
 Are CNC spindle suppliers expanding local repair for five-axis machines?Explore cnc spindle supplier trends in local repair for five-axis machines. Learn how to verify repair capacity, compare exchange options, and choose support that reduces downtime.
 China’s Base Oil Imports Hit 2026 Low in September; Top Three Suppliers Account for 82.5%China’s base oil imports hit a 2026 low of 67,400 tonnes in September, with three origins accounting for 82.5%. Explore the data and implications for sourcing and supply risk.
 How to verify batch quality with an industrial lubricating oils exporterBuying from an industrial lubricating oils exporter? Learn how to verify batch test results, sampling, and traceability to reduce purchasing risks and protect equipment.
 How to set relubrication intervals for industrial maintenanceImprove industrial maintenance with smarter relubrication intervals. Learn how to balance bearing conditions, grease quantity, and monitoring to reduce downtime and avoid costly failures.
 How to spot misleading claims on eco-friendly baby productsShopping for ecofriendlybabyproducts? Learn to spot greenwashing, verify certifications, and assess material and disposal claims so you can choose with confidence.
 John Crane Signs Three-Year Agreement to Improve Phosphate Mine Seal ReliabilityJohn Crane's three-year agreement targets phosphate mine seal reliability with on-site expertise and mechanical seal solutions. Explore its potential to reduce downtime.
 CNC Routing Plywood: Testing Tooling and Hold-Down TogetherExplore ZD1325 plywood routing capabilities by testing tooling and hold-down together. Learn how to assess edge quality, part retention, and repeatability before you invest.
Search News
Popular Tags